
User needs drive the product
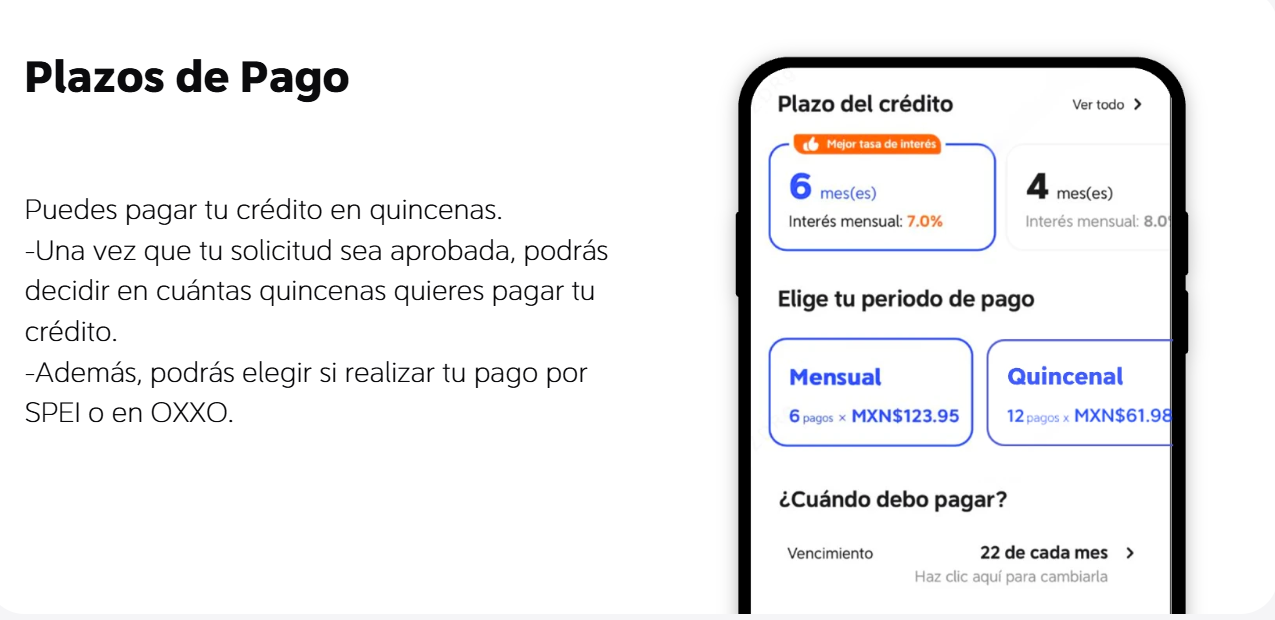
Consumers want predictable, mobile-first ways to split payments without juggling paperwork; DiDi addresses that demand by integrating lending into everyday flows. The product thread starts at checkout and ties into services like didi prestamos, which removes friction for users who need quick credit decisions. From a planner’s perspective, the user-centric model prioritizes low latency, clear pricing, and minimal steps between decision and disbursement.
How the model maps to BNPL and “buy now, pay later”
Operationally, this is BNPL implemented inside a mobility-and-services ecosystem. The stack mixes mobile wallet features, API-driven underwriting, and lightweight KYC to approve small-ticket credit in real time. That combination shortens time-to-credit and supports prestamos en linea al instante for purchases that otherwise stall at checkout. Designers must balance approval speed with basic risk controls — think credit scoring plus simple affordability checks rather than full traditional underwriting.
Concrete architecture and control points
At the technical level, success rests on three layers: a customer-facing app, a decisioning engine, and a reconciliation/collections module. The decisioning engine uses rules and thin-model credit signals to produce near-instant decisions; the front end communicates options and displays interest rate and fee breakdowns plainly. For product teams, the lesson is to treat credit like a feature — one that must be reversible and auditable. Real-world anchor: regulatory clarity after Mexico’s 2018 Fintech Law created a safer operating perimeter for platforms to test these services at scale.
Risks, controls, and user trust — a planner’s checklist
Credit implies risk. Controls must be visible and enforceable. Implement rate caps, clear consent flows, and a robust dispute process. Monitor early-warning signals such as repeat partial payments or sudden increases in utilization. User communication is part of control — transparent billing messages reduce late payments and preserve lifetime value. The product must also ensure compliance with consumer-protection rules and data-privacy standards.
Common mistakes and practical alternatives
Teams often over-index on approval speed and under-invest in post-approval engagement — a misstep that raises default rates. Another mistake is opaque fee structures; users reject complexity. Alternatives include small revolving lines with clear minimum payments, installment schedules with fixed interest, or partnering with incumbent banks for larger-ticket underwriting. If quicker credit is the priority, combine lightweight behavioral signals with third-party identity verification rather than full traditional credit bureau dependence — it reduces friction without removing key risk controls.
Operational trade-offs — a short, practical note
Scaling requires trade-offs between margin and acceptance. Higher acceptance improves retention but increases loss provisioning. Lower margins demand efficient collections and tight fraud screening. Teams should instrument unit economics continuously — acquisition cost, average order value, and loss rate must be visible daily — and iterate on underwriting rules to optimize the balance.
Three golden rules for evaluation
1) Approval quality over sheer speed: measure post-approval repayment rates within 30 and 90 days. 2) Transparency metrics: track help-desk volume tied to billing confusion and aim to reduce it by half within three months. 3) Regulatory alignment and controls: ensure audit trails, limit testing to compliant zones, and maintain strong data governance. These metrics reveal if a BNPL feature is healthy for both user experience and balance-sheet stability.
DiDi Finanzas naturally fits here as a solution that embeds credit where users already transact — making payments simple and manageable for everyday needs. —