
Quick comparison that matters
Traditional banks, big fintechs, and platform-backed lenders all promise perks. What sets didi finanzas apart is a focus on merchant promotions tied directly to user behavior — not just long credit histories. This comparative insight shows where DiDi Finanzas fits: convenience via digital onboarding, targeted merchant offers, and a simpler route to a credit line for everyday users. The narrative below weighs those features against standard credit underwriting and bank card offers.
Where DiDi Finanzas wins vs. banks and cards
Banks still lead on broad acceptance and sometimes lower APR for prime borrowers, but they can be slow on approvals and strict with risk assessment. Big fintechs may offer fast approvals but often require heavy documentation or external credit scores. DiDi Finanzas combines lightweight digital onboarding with merchant-linked promotions — a useful mix for people who spend on rides, food, and local services. The product model reduces friction: instead of lengthy paperwork you get tailored rewards and periodic credit boosts tied to activity and repayment patterns. For many users, that beats a generic rewards card.
How the product works in practical terms
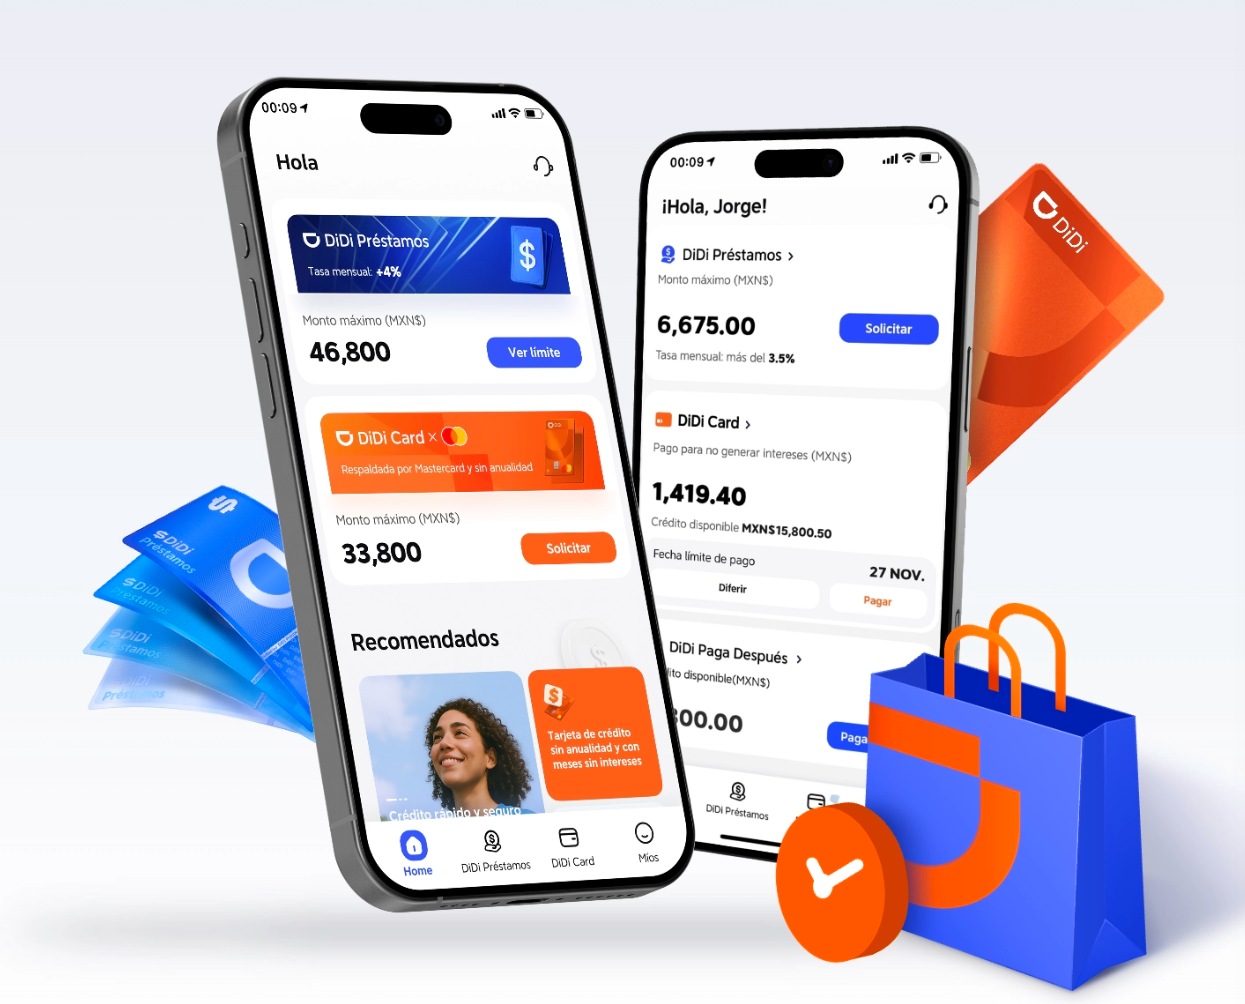
At its core: app-driven underwriting, behavioral signals, and promotional partnerships. The didi card is issued after a short verification flow and uses transaction history plus platform behavior for risk scoring. That lowers entry barriers for those with thin credit files. Industry terms here include credit underwriting, credit line, and APR — but the headline is simpler: you get promotions that match your spending, and credit decisions that weigh recent behavior as heavily as past history. Visit the didi finanzas app to see how the steps map out in the interface.
Alternatives and common mistakes
Users often pick a card for a single big reward and then miss the overall cost: high APRs, missed grace periods, or narrow merchant categories. Alternatives: traditional rewards cards if you regularly qualify for low APRs; retail cards when you shop mainly at one chain; or other platform cards when you want broad travel perks. Common mistakes include over-relying on introductory promos and ignoring effective APR after the promo ends — that’s where many people lose value. Also, don’t assume a platform card replaces the need for a basic bank relationship; it complements it.
Real-world anchor: market context and behavior
In Mexico City — where rideshare apps are woven into daily travel — customers value fast approvals and merchant benefits more than cosmetic points. World Bank and regional studies repeatedly show parts of Latin America still have low formal credit access, so solutions that accept alternative data can matter at scale. DiDi’s presence in urban mobility gives it direct merchant channels for promotions, and that operational edge is a real advantage when compared to pure-play banks.
Risks, transparency, and what to check
Look for clear disclosure on APR, late fees, and how promotions are applied. Platform-linked underwriting can be opaque; insist on plain-language terms. Also monitor how merchant promotions affect your statement credits — stackable perks sometimes have expiry or minimum-spend rules. — Be cautious about letting promotional offers dictate long-term borrowing.
Three golden rules for choosing the right card
1) Measure total cost, not just headline rewards: compare APR plus fees against projected use. 2) Match reward structure to real spending patterns: choose promos where you actually shop and travel. 3) Confirm transparency in underwriting and dispute resolution; a clear path to contest charges matters. Apply these metrics and you’ll see where DiDi Finanzas aligns with your needs versus a standard bank card.
Final take
DiDi Finanzas positions itself as a pragmatic bridge for people who want immediate, usable perks and a simpler route to credit without a cosigner. For customers who live in app-driven ecosystems and value merchant promotions over point hoarding, it can be a smarter choice than waiting for a traditional bank approval. DiDi Finanzas — practical, local-aware, and tuned to everyday spending. –